Corporate financial distress and banking sector vulnerability: an integrated risk assessment approach
Keywords:
Corporate Financial Distress, Banking Sector Vulnerability, Systemic Risk, Early-Warning Models, Machine Learning, Credit Risk.Abstract
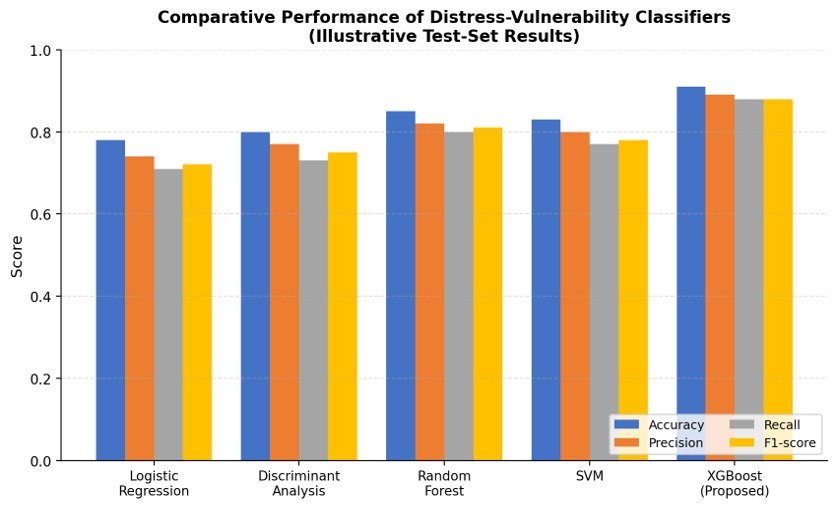
The fragility of the banking sector and the financial distress of corporations are closely related but most of the existing literature considers the development of financial distress of firms and bank's solvency problems as two separate issues. In this research, we offer a multi-layer framework of investigating the connections from firm-level financial distress to bank-level vulnerability by multiple measures, including accounting ratios, market-based metrics and loan-exposure concentration ratios. The framework integrates classical distress-prediction approaches, such as discriminant analysis, logistic regression and structural credit-risk theory with the ensemble machine-learning approach to obtain an interpretable systemic early warning signal. The methodology features four steps: (i) firm-level distress probabilities are estimated based on financial and market indicators; (ii) these distress probabilities are aggregated to obtain exposure-weighted vulnerability measures for banks; (iii) individual banks' vulnerability measures are wrought in with solvency and liquidity indicators; and (iv) a gradient-boosting ensemble (GBE) classifier is used to estimate the systemic vulnerability indicator. The efficiency of the approach proposed is illustrated through a simulated but realistic set of data on the financial characteristics of the distressed firms and distressed banks. Moreover, the gradient-boosting model with integrated feature ranking is superior to the other classic models like logistic regression, discriminant analysis, random forest model, and support vector machines in terms of accuracy, precision, and AUC. The framework has recently demonstrated both an increase in the predictive power of the models, as well as making them more interpretable through an understanding of the mechanisms by which firm-level distress spreads to the risk of the banking sector. The proposed architecture provides a scalable framework for systemic risk monitoring, while empowering regulators, financial institutions, and macroprudential authorities to reinforce financial stability and to detect risks in a timely and more reliable manner.
Published
How to Cite
Issue
Section
Copyright (c) 2026 Sanjana Amarjeet

This work is licensed under a Creative Commons Attribution 4.0 International License.